Applicant Data Capture
More Info
In order for the Amount's Intelligent Decisioning Waterfall to have maximum impact, the applicant's data is collected along the applicant's journey. Along that applicant journey Amount will leverage ThreatMetrix to ensure device compliance, Smarty to prefill and validate address information, and Prove to prefill Name, Address, & Social Security Number based upon the applicant simply filling in the mobile number.
ThreatMetrix profiles the device being used to complete the application to return hundreds of attributes, including IP address, DNS, ISP, VPN, virtual machine use, OS, browser, physical location, and network activity of that device. Data such as IP address, operating system and browser configuration are used to assign a "device fingerprint" to devices that interact with the application. This data, in addition to cookie based tracking, is used to identify devices that have been used to submit applications, and support link analysis that may be indicative of one fraudster using multiple stolen identities.
A reseller of the U.S. Postal Service data, which is used to screen for risky address types, ZIP code mismatches, and standardize addresses into USPS format.
Featured Vendors
Pre Credit Eligibility Rules
More Info
Eligibility rules are run before a credit report is pulled. The rules will be run from top to bottom and the order will be used to prioritize which decline reasons are displayed in the adverse action template.
Reg O
Franchise
Marijuana
Politically Exposed Person
Money Service
Embassy
Residency Status
Currency Shipping
Adult Entertainment
Individual Income
Third Party Payment Processor
Consumer Lending
Non Profit
Applicant Applied Too Recently
Digital Currency
Trust
Prior Confirmed Fraud
Property Foreclosure (self attest)
Footprint
Minimum Age
General Foreclosure (self attest)
Stated Sales
Prohibited Industry
Delinquent Federal Debt (self attest)
Internal Debt Refinance
Business Tenure
Delinquent Tax (self attest)
Existing LOC
High Risk Business Tenure
Judgment (self attest)
Ownership Change
Internet Gambling
Lawsuit (self attest)
Post Credit Consumer Rules
More Info
Third party reports are pulled, then rules are executed automatically from top to bottom based upon product configuration. Configuration options include hard declines with automated notice of adverse action (NOAA) templated communications or soft declines requiring manual review; various thresholds are also self-configurable for each rule.
Bureau No Hit
Score < 700 and Number Inquires > 6 in Last 6 Months
No Score
Number Inquiries in Last 6 Months > 7
Deceased
Number Inquiries in Last 3 months > 5
Oldest Tradeline Age < 24 Months
Number of Inquiries in Last 2 weeks > 4
Score < 660
Revolving Utilization > 90% for 4 or more Revolving Tradelines and Score < 700
Score < 720 and High Risk Industry
Revolving Utilization > 70% and Score < 700
Foreclosure Ever > 1
Revolving Utilization > 70% with Total Outstanding Balance > $2K
Foreclosure 24 Months > 0
DTI > 55%
Number of 90 Days Delinquencies w/in 6 Months > 1
Number of Bankruptcies in Last 48 months > 0
Number of 60 Days Delinquencies w/in 12 Months > 1
Credit Freeze
Number of Delinquencies in Last 24 months > 2
Fraud Statement
Number of Unpaid Public Records or Collections > 0
Active Duty Alert Present
LNRV Report No Hit
Active Duty Alert with Fraud Victim Statement Present
LNRV Bankruptcies > 1
Fraud Victim Statement Present
LNRV Felony > 0
Active Duty with Extended Fraud Victim Statement Present
LNRV Evictions > 1
Extended Fraud Victim Statement Present
LNRV Evictions in Last 24 Months > 0
Ratio of Revolving Balance to Stated Income > 0.7
LNRV Wealth Index = 1
Oldest Tradeline < 36 Months
LNRV Number of Derogatory Records > 2
Number of Derog Public Records > 2
LNRV Total Unsatisfied/Unpaid Liens > $5K
Number of 90 Days Delinquencies w/in 24 Months > 1
LNRV Total Liens Ever > 5
Number of 60 Days Delinquencies in last 24 Months > 1
LNRV Total Liens Outstanding > 1
Number of Accounts 60 Days Past Due w/in 6 Months > 0
Featured Vendors
Post Credit Business Rules
More Info
After the Experian Small Business Financial Exchange (SBFE) credit report is pulled, decline rules are run using the report. The rules will be run from top to bottom and the order will be used to prioritize which decline reasons are displayed in the adverse action template.
Bureau No Hit
Business Bankruptcies < 8 Years
Business Bankruptcies Ever
Number of Delinquencies > 31 Days Over Last 12 Months > 4
Number of Unsatisfied Charge Offs Last 6 Months
Total Current Past Due > $1,000
Number of Unsatisfied Charge Offs Ever
Number of Business Liens > 2
Charge Offs Totaling > $2,000
Number of Business judgements > 1
Days Delinquent > 60 Days
Total Liens & Judgments > $10,000
Number of Delinquencies > 61 Days Over Last 12 Months
Business Debt to Sales > 50%
Featured Vendors
Post Credit Consumer Rules for Beneficial Owners
More Info
The same Post Credit Consumer Rules executed for the primary applicant apply here as well. Third party reports are pulled, then rules are executed automatically from top to bottom based upon product configuration. Configuration options include hard declines with automated notice of adverse action (NOAA) templated communications or soft declines requiring manual review; various thresholds are also self-configurable for each rule.
Please see all rules under Post Credit Consumer Rules
Featured Vendors
Blended Score Policy
More Info
Amount uses a concept of "decisioned guarantor" for the SBFE blended report and is only run for one applicant. There is a check to see which applicant has the highest ownership stake and then the policy is run for that applicant. If there is an ownership tie at the highest level, then the policy is run for the applicant with the highest credit score. If it's still a tie, then it's only run for the primary applicant.
Blended Score < 600
Blended Score Not Available
Featured Vendors
Cash Flow Underwriting
More Info
These are the configurable rules to determine whether an applicant should have business cash flow verified. If an applicant triggers any of the rules configured "on," they will be required to verify business cash flow.
Force all applicants to verify business cash flow
Application Rejected in Past 180 Days
Manual Escalation - Ops Team Required Cash Flow Verification
Blended Score 600 to 699
Mitigation Strategy - Last (3) Months of Bank Statements (Finicity)
Counter Offer Strategy
If configured ON, the platform attempts to keep the loan amount the same by increasing the term of the loan. If this is possible, it takes the term closest to the one selected. If not possible, it calculates the highest loan amount eligible with the term closest to the one selected. It is then possible to configure if adverse action notices are sent if declined.
Featured Vendors
Account Verification
More Info
The Amount platform facilitates validation and verification of an applicant's account information using a combination of third party data-driven, applicant-driven, and agent-driven workflows. Default configurations prioritize lowest-friction options first in order to increase applicant approval rate and reduce reliance on manual document reconciliation as an account verification technique.
Finicity enables applicants to use their online banking credentials to provide confirmation or ownership and authenticity of account information.
Giact or ValidiFI are fraud data sources Amount will leverage when an applicant chooses to manually enter their Account / Routing Number for account connectivity for disbursement. Account / Routing Number Validation and Account Ownership Validation are performed and if necessary Statement or Voided Check uploads may be requested.
Featured Vendors
KYB Checks
More Info
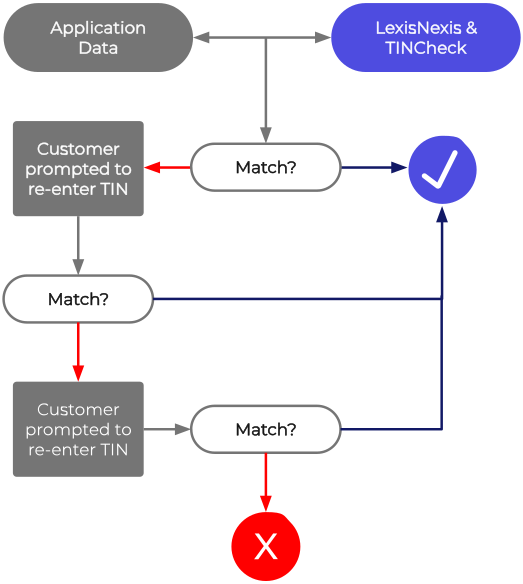
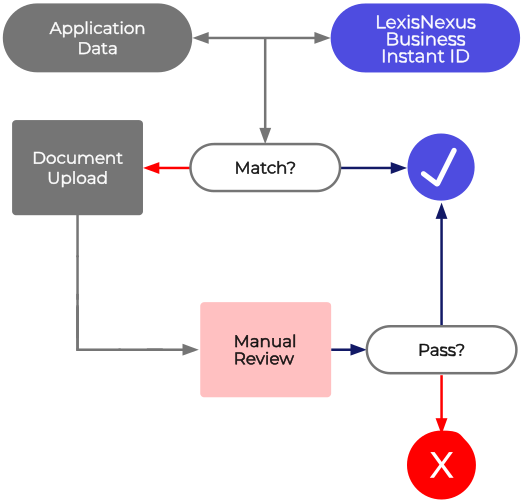
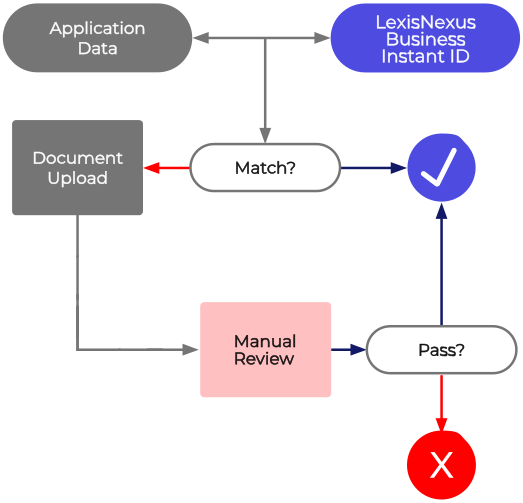
These Know Your Business (KYB) selections dictate the policy which applying businesses are screened against as a control for business verifications leveraging LexisNexis Business Instant ID (BIID) & TINCheck. Applicants may be required to re-key data or upload tax returns, business form documents, or a government-issued business license. For Secretary of State Verification a good standing certificate may be required for upload.
Featured Vendors
KYC / CIP Checks
More Info
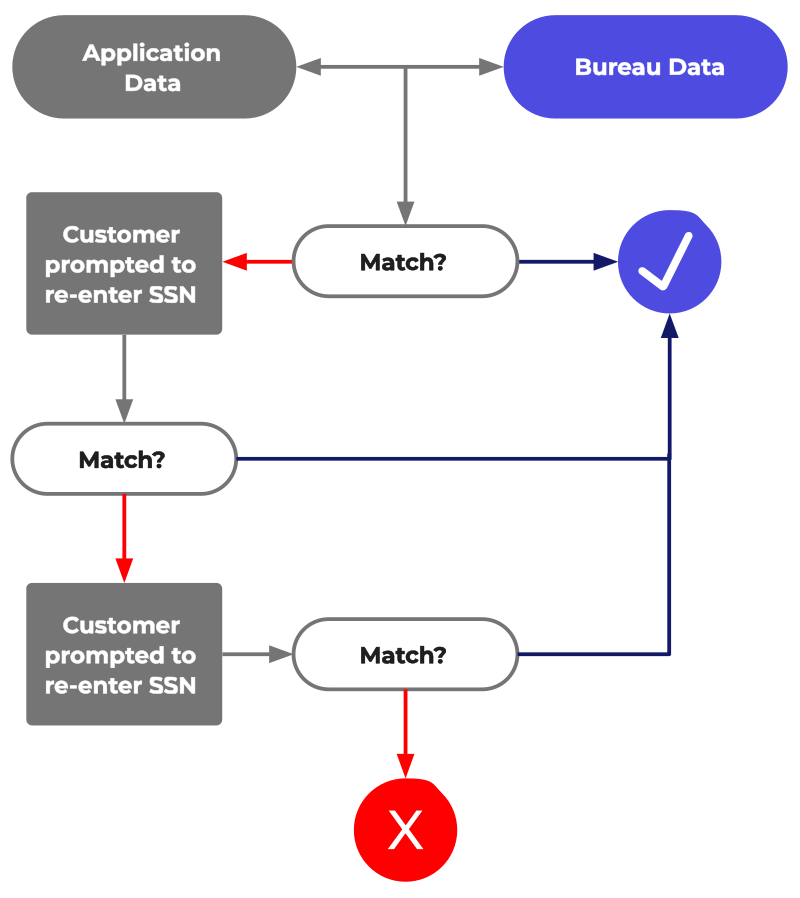
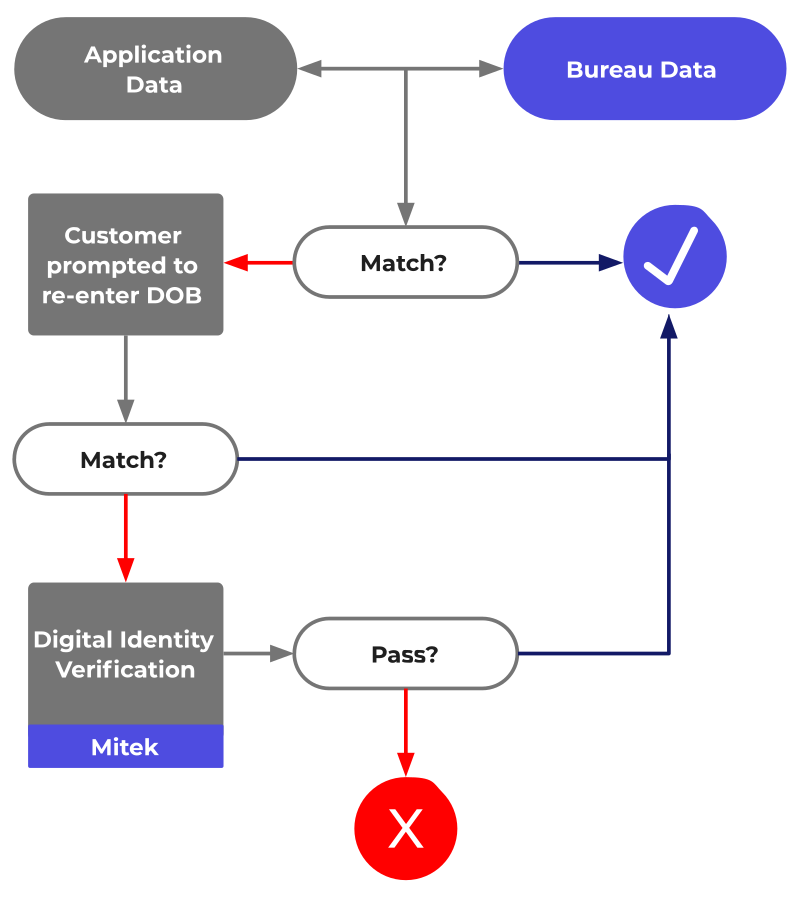
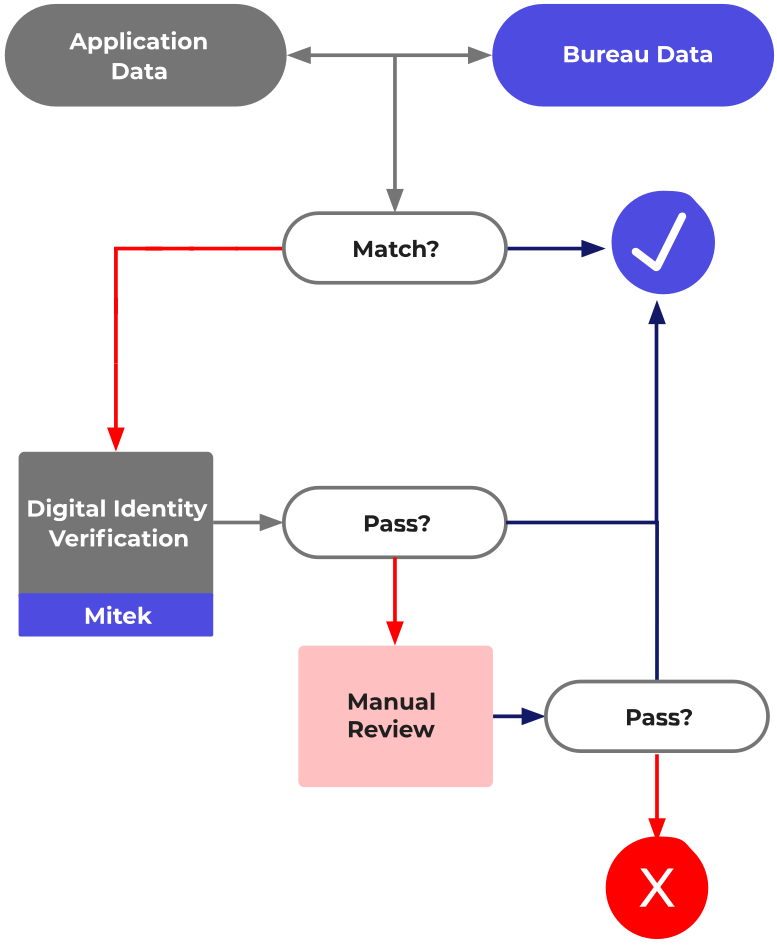
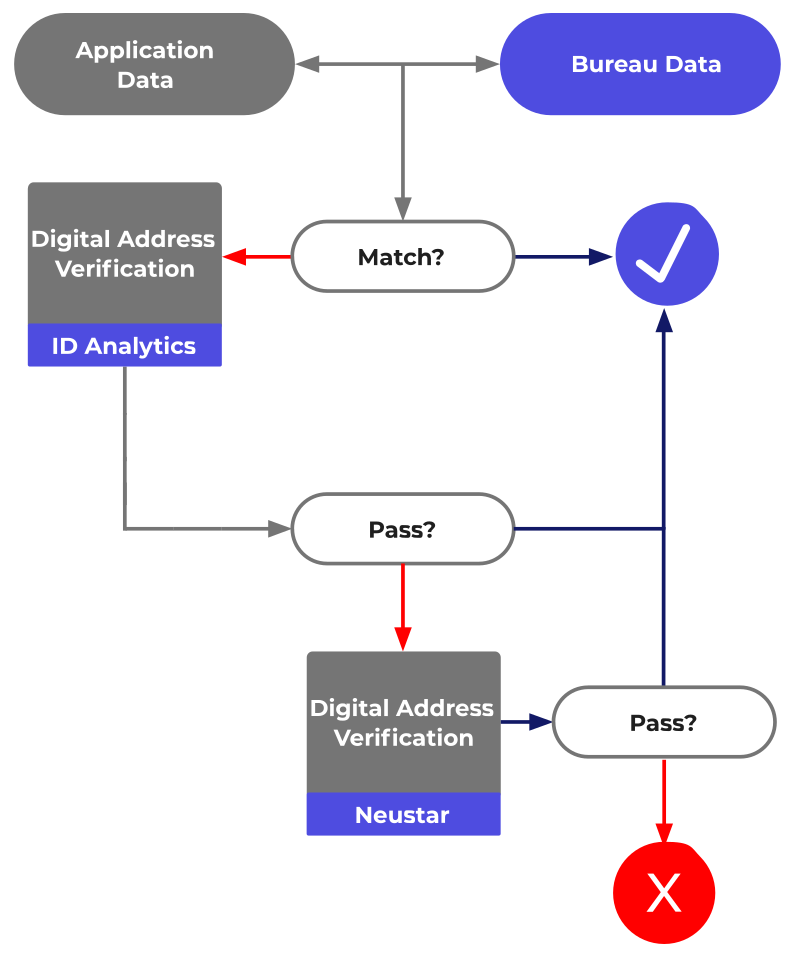
By default, the Amount platform will perform Know Your Customer (KYC) / Customer Identification Program (CIP) checks for four points of Personally Identifiable Information (PII) provided by the applicant against the same data points within the credit report. In the event of a data mismatch, the applicant is prompted with a series of dynamic tasks prior to the display of any rates and terms.
Featured Vendors
FCRA Alerts
More Info
Amount uses the applicant's credit bureau report to identify if applicants have any consumer fraud alerts in their credit report. If an applicant has an initial fraud, extended fraud, or active duty fraud alert in their bureau file, the application will be pending. System controls prevent the application from being approved until the alert is reconciled.
Initial Identity Fraud Alert
Extended Identity Fraud Alert
Active Military Alert
Featured Vendors
Fraud Model
More Info
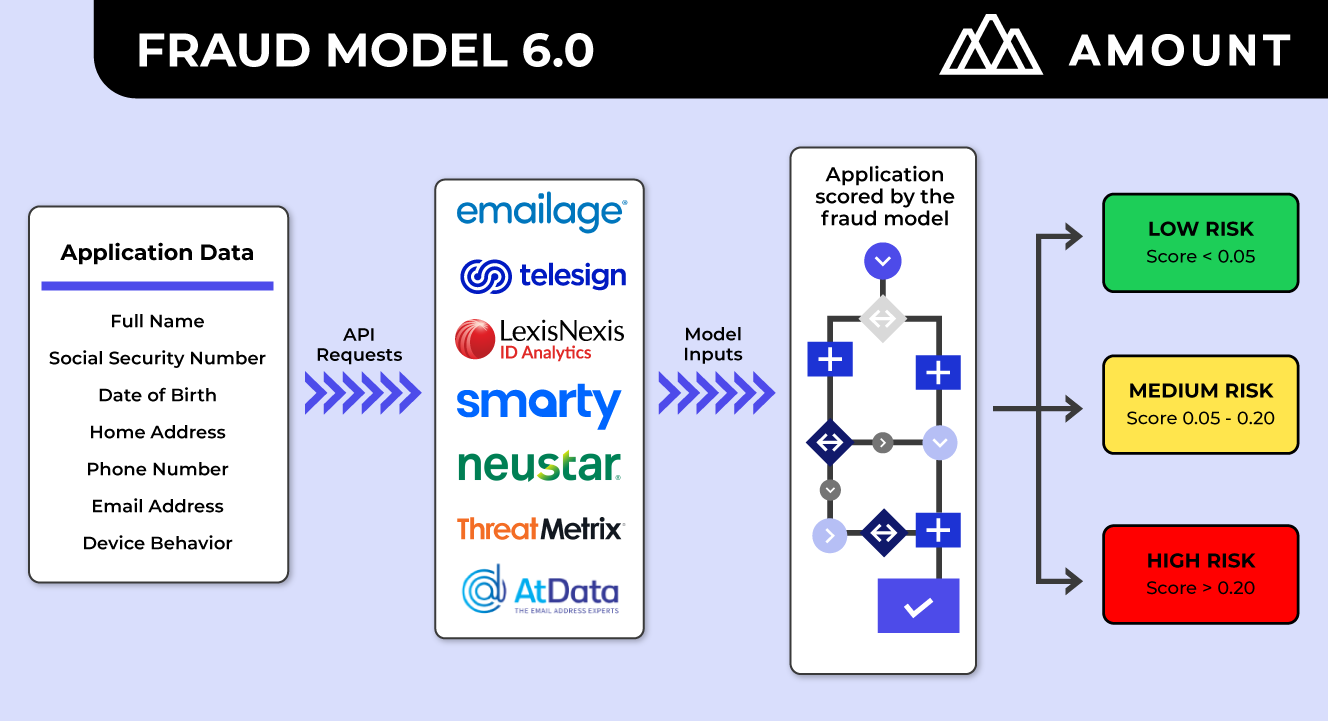
We have leveraged over a decade of experience as a direct lender to craft a fraud and identity verification solution. We have curated the best data sources available, targeting all aspects of an applicant's identity, including device, email, phone, address, bank account and velocity attributes. The Amount platform uses a proprietary machine learning-developed hard fraud model to assess applicants' fraud risk. This fraud model returns a simple score predicting the likelihood that a given application is fraudulent. This score, in addition to attributes from the below data sources, will be used to construct fraud rules resulting in enhanced identity verification challenges and/or manual fraud reviews.
Fraud Model
A consumer database that provides name-to-email associations, email address age, activity, and overall fraud rating for a given email address.
Given a phone number, TeleSign leverages telecom data to return the identity associated with that phone number, as well as details about the phone itself, including the provider, phone type, and date that the number became active.
A consumer database that provides attribute velocity data and other risk ratings for an applicant's personal, contact and banking information.
A reseller of the U.S. Postal Service data, which is used to screen for risky address types, ZIP code mismatches, and standardize addresses into USPS format.
Neustar uses telecom data to establish linkages between the applicant and the phone number provided, as well as risk scores related to the applicant's email and physical address.
ThreatMetrix profiles the device being used to complete the application to return hundreds of attributes, including IP address, DNS, ISP, VPN, virtual machine use, OS, browser, physical location, and network activity of that device. Data such as IP address, operating system and browser configuration are used to assign a "device fingerprint" to devices that interact with the application. This data, in addition to cookie based tracking, is used to identify devices that have been used to submit applications, and support link analysis that may be indicative of one fraudster using multiple stolen identities.
A consumer database that provides information on how old and active an email address is in the Internet ecosystem.
Compliance Screening
More Info
Amount has partnered with ComplyAdvantage to screen applicants against the OFAC (Office of Foreign Assets Control) - SDN (Specially Designated Nationals and Blocked Persons) sanctions list. Applicants flagged as possible hits pending until an AML (Anti-Money Laundering) / BSA (Bank Secrecy Act) investigator reviews the application for risk and either rejects the application or resolves a task as a condition of approval.
OFAC
BSA
Sanctions
AML
Featured Vendors
Manual Review / Operations Tasks
More Info
Any application that has been soft declined because it did not pass a step in Amount's Intelligent Decisioning Waterfall or requires additional manual review is presented to authorized Financial Institution agents (Underwriter, Operations, Compliance, Member/Customer Support, Credit Risk, and/or Fraud Prevention) for decisioning. Authorized agents can also leverage Amount's AI Policy Optimizer and Rule Builder to make adjustments to policies where appropriate.
Applications are viewed in Amount's Queue Manager, which includes records of application activity, agent tasks, and third party reports.
Applications will be screened against an identity policy ruleset and flagged applications will be pending in a queue until an operations agent can manually review the application for identity risk and decision manually in Amount's Queue Manager.
Applications will be screened against a credit policy ruleset and flagged applications will be pending in a queue until a credit risk agent can manually review the application for credit risk and decision manually in Amount's Queue Manager.
Applications will be screened against a fraud policy ruleset and flagged applications will be pending in a queue until a fraud agent can manually review the application for fraud risk and decision manually in Amount's Queue Manager.
Featured Vendors