Intelligent Decisioning Waterfall - Consumer Deposits
Robust real-time orchestration with enhanced risk mitigation, incorporating friction only where necessary and supported by comprehensive audit logs.
Direct Amount contracting and orchestration with third-party data sources to create a comprehensive out-of-the-box origination solution that highlights our Superior Risk Decisioning and Arriving With Lending Intelligence value propositions.
Applicant Data Capture

More Info

In order for the Amount's Intelligent Decisioning Waterfall to have maximum impact, the applicant's data is collected along the applicant's journey. Along that applicant journey Amount will leverage ThreatMetrix to ensure device compliance, Smarty to prefill and validate address information, and Prove to prefill Name, Address, & Social Security Number based upon the applicant simply filling in the mobile number.

ThreatMetrix

ThreatMetrix profiles the device being used to complete the application to return hundreds of attributes, including IP address, DNS, ISP, VPN, virtual machine use, OS, browser, physical location, and network activity of that device. Data such as IP address, operating system and browser configuration are used to assign a "device fingerprint" to devices that interact with the application. This data, in addition to cookie based tracking, is used to identify devices that have been used to submit applications, and support link analysis that may be indicative of one fraudster using multiple stolen identities.

Smarty

A reseller of the U.S. Postal Service data, which is used to screen for risky address types, ZIP code mismatches, and standardize addresses into USPS format.

Prove

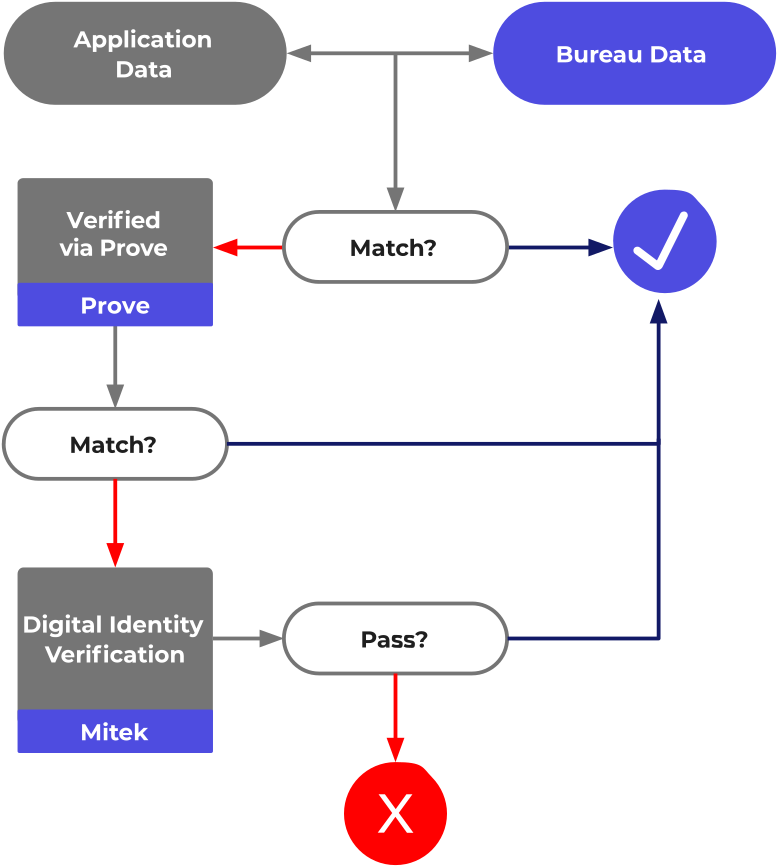
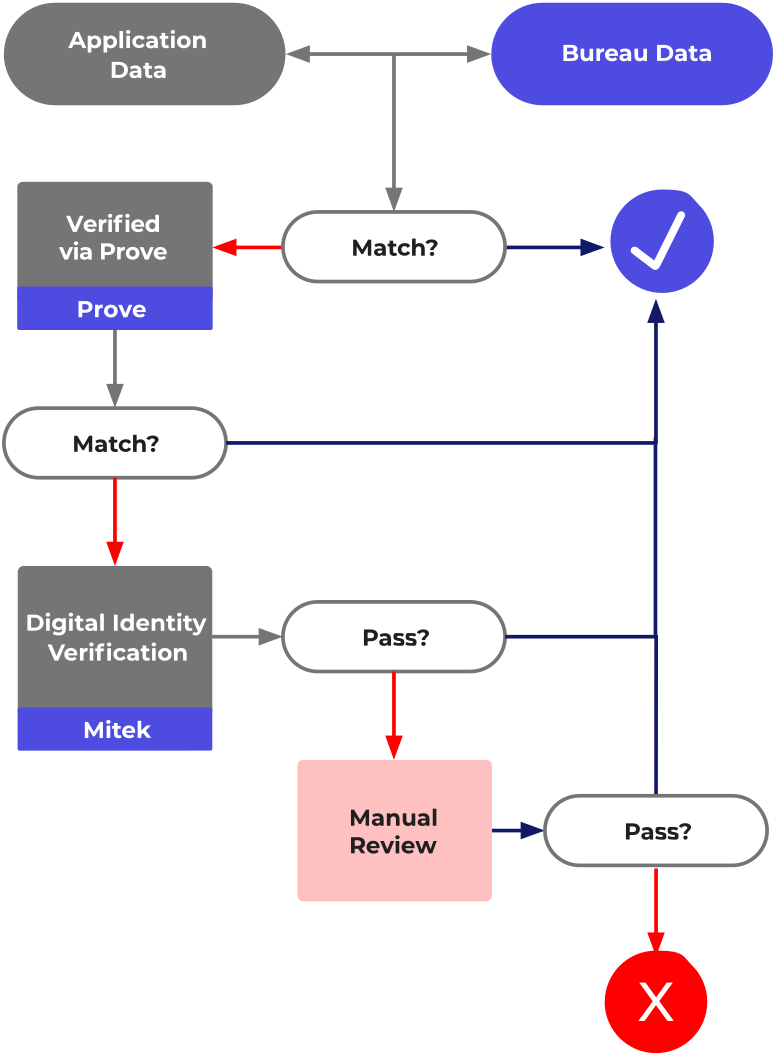
In order to allow our customers to satisfy Know Your Customer (KYC) regulations and validate applicant personal information via automated methods, Amount has integrated Prove's Identity Eligibility and Identity Pre-Fill APIs.

Featured Vendors

Eligibility Rules

More Info

Eligibility rules are run before a credit report is pulled. The rules will be run from top to bottom and the order will be used to prioritize which decline reasons are displayed in the adverse action template.

Minimum Age

Geographic Footprint

Minimum Gross Income

Citizenship Status

Prior Confirmed Fraud

Declined Too Recently

Credit Rules

More Info

After a credit report is pulled, decline rules are run using the report. The rules will be run from top to bottom and the order will be used to prioritize which decline reasons are displayed in the adverse action template.

ChexSystems® Freeze

Number Closures

ChexSystems® QualiFile® Reason Code

Recommended Decision Accept

Consumer No Data

Recommended Decision Decline

Low QualiFile® Score - Decline

Recommended Decision Review

Low QualiFile® Score - Pend

Featured Vendors

KYC / CIP Checks

More Info

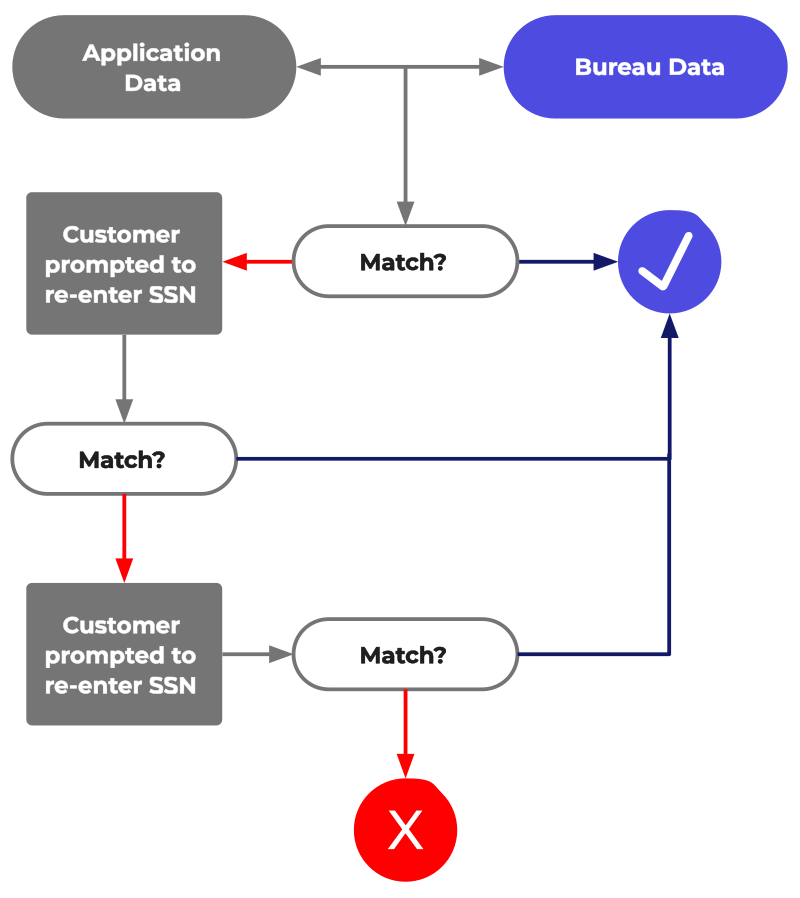
By default, the Amount platform will perform Know Your Customer (KYC) / Customer Identification Program (CIP) checks for four points of Personally Identifiable Information (PII) provided by the applicant against the same data points within the credit report. In the event of a data mismatch, the applicant is prompted with a series of dynamic tasks prior to the display of any rates and terms.

SSN Verification
DOB Verification
Name Verification
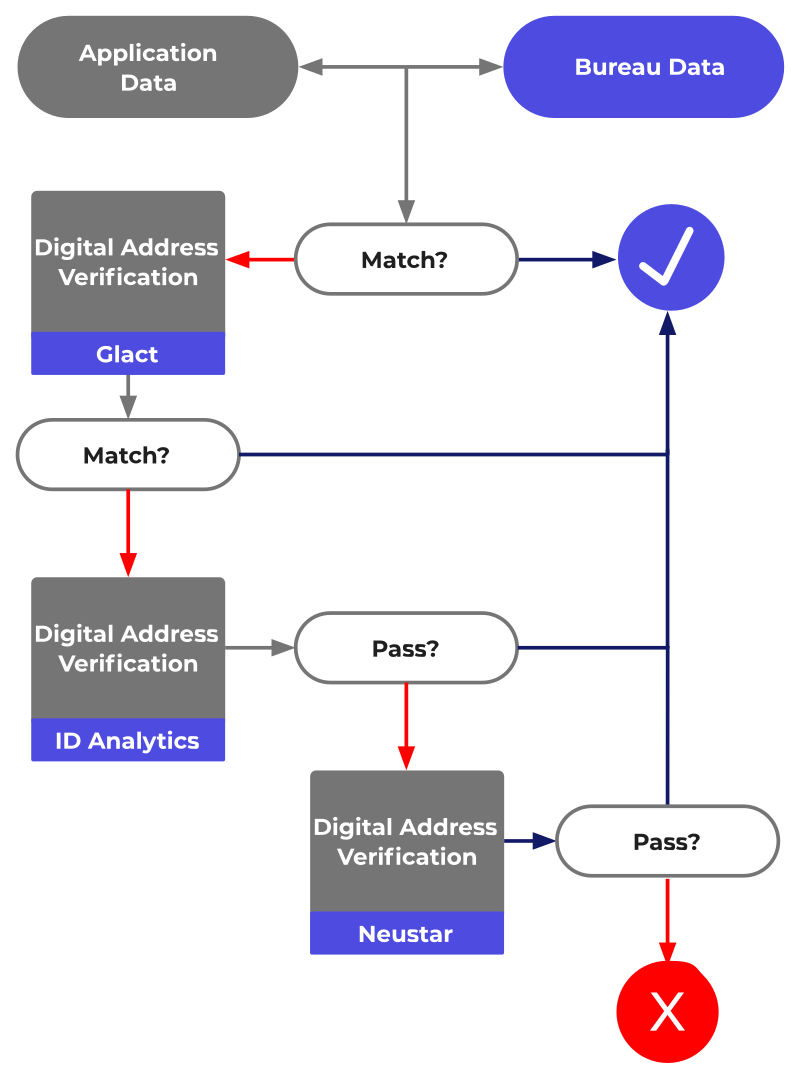
Address Verification

Featured Vendors

FCRA Alerts

More Info

Amount uses the applicant's credit bureau report to identify if applicants have any consumer fraud alerts in their credit report. If an applicant has an initial fraud, extended fraud, or active duty fraud alert in their bureau file, the application will be pending. System controls prevent the application from being approved until the alert is reconciled.

Initial Identity Fraud Alert

Extended Identity Fraud Alert

Featured Vendors

Fraud Model

More Info

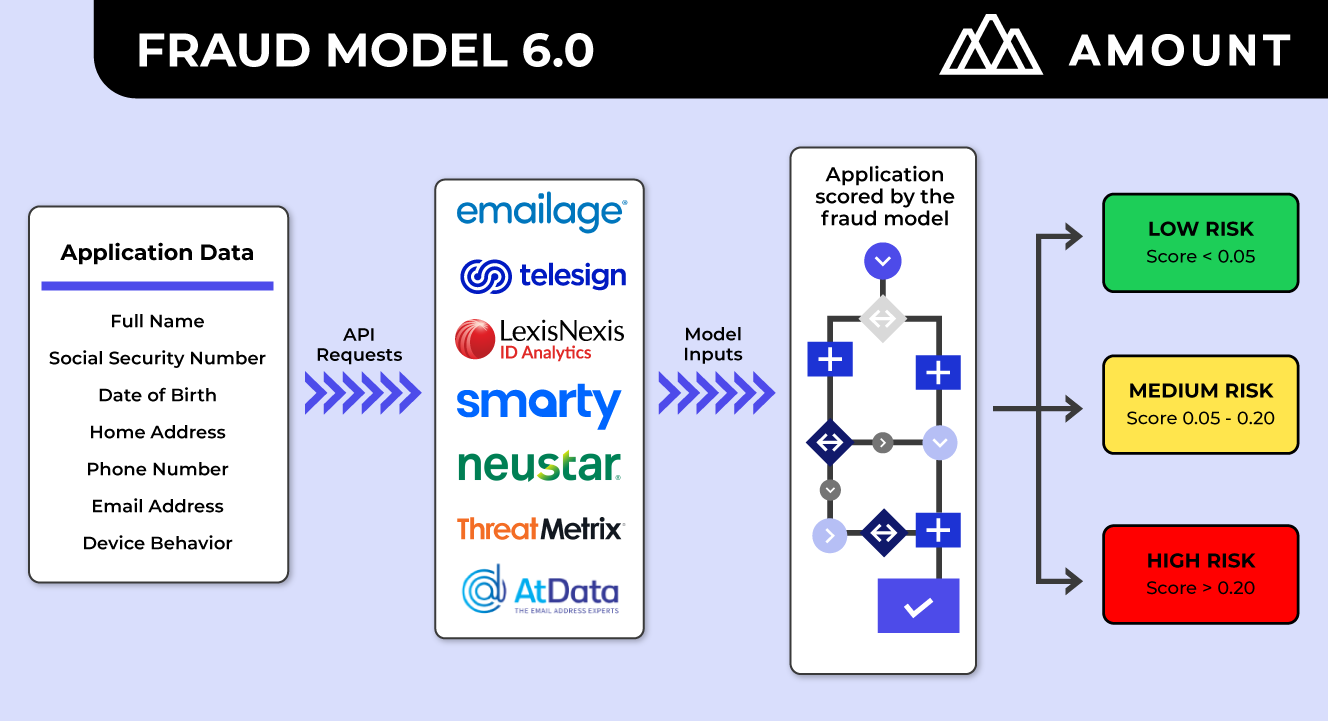
We have leveraged over a decade of experience as a direct lender to craft a fraud and identity verification solution. We have curated the best data sources available, targeting all aspects of an applicant's identity, including device, email, phone, address, bank account and velocity attributes. The Amount platform uses a proprietary machine learning-developed hard fraud model to assess applicants' fraud risk. This fraud model returns a simple score predicting the likelihood that a given application is fraudulent. This score, in addition to attributes from the below data sources, will be used to construct fraud rules resulting in enhanced identity verification challenges and/or manual fraud reviews.

Fraud Model

Emailage

A consumer database that provides name-to-email associations, email address age, activity, and overall fraud rating for a given email address.

TeleSign

Given a phone number, TeleSign leverages telecom data to return the identity associated with that phone number, as well as details about the phone itself, including the provider, phone type, and date that the number became active.

ID Analytics

A consumer database that provides attribute velocity data and other risk ratings for an applicant's personal, contact and banking information.

Smarty

A reseller of the U.S. Postal Service data, which is used to screen for risky address types, ZIP code mismatches, and standardize addresses into USPS format.

Neustar

Neustar uses telecom data to establish linkages between the applicant and the phone number provided, as well as risk scores related to the applicant's email and physical address.

ThreatMetrix

ThreatMetrix profiles the device being used to complete the application to return hundreds of attributes, including IP address, DNS, ISP, VPN, virtual machine use, OS, browser, physical location, and network activity of that device. Data such as IP address, operating system and browser configuration are used to assign a "device fingerprint" to devices that interact with the application. This data, in addition to cookie based tracking, is used to identify devices that have been used to submit applications, and support link analysis that may be indicative of one fraudster using multiple stolen identities.

AtData

A consumer database that provides information on how old and active an email address is in the Internet ecosystem.

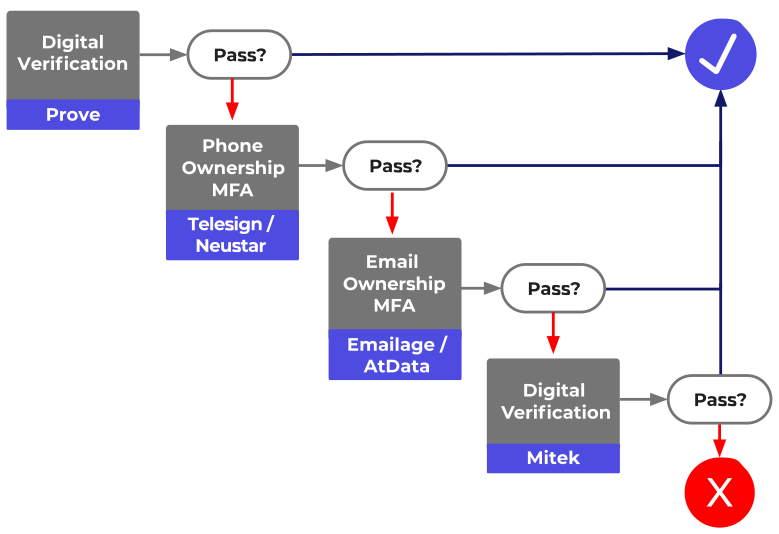
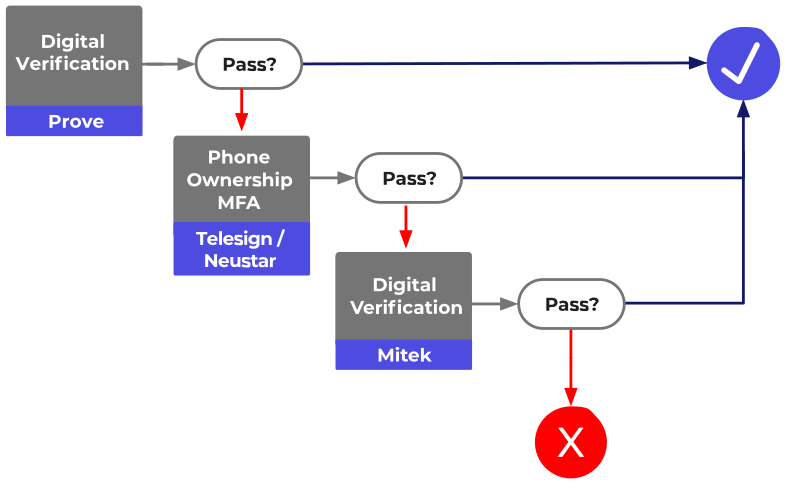
Identity Verification

More Info

As data is returned from the application data, bureau data, and various third-party data sources, the Amount platform looks for certain indicators of identity-related fraud.

Identity Verification Rules

Risk screening data is applied against an applicant's identity verification ruleset. This ruleset determines which risk tier is assigned to an application and dictates identity verification requirements for that application.

ThreatMetrix
  • Suspicious Device Profile
  • Missing Device Profile
  • Virtual Machine Use (VPN)
Credit Bureau
  • FCRA Fraud Alert
  • Missing Vendor Report
Smarty
  • Address Verification
  • Missing Vendor Report
Amount Fraud Model
  • Fraud Score
  • Unable to Score
Emailage
  • Young E-mail Address (<60 days)
  • Missing Vendor Report
AtData
  • Young E-mail Address (<60 days)
  • Missing Vendor Report
ComplyAdvantage
  • OFAC
  • PEP Screening
ID Analytics
  • Missing Vendor Report
Neustar
  • Missing Vendor Report
Telesign
  • VoIP Phone Number
  • Missing Vendor Report

Featured Vendors

Identity Verification Risk Segmentation & Mitigation

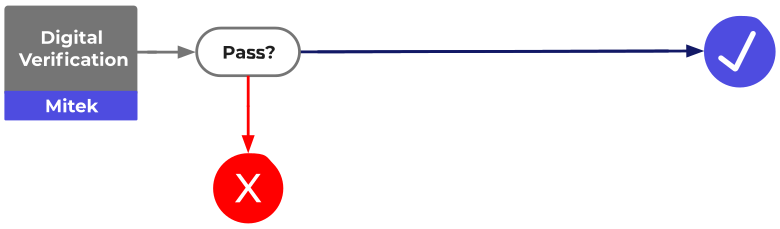
By default, each application is considered low-risk. When an application is screened against an applicant's identity verification ruleset, it is assigned a risk tier rating: low risk (no rules triggered), medium risk, or high risk.

Low Risk Rules

  • By default, all applicants who do not trigger any preconfigured risks are considered low-risk.

Medium Risk Rules

  • Young email address
  • Missing fraud model score
  • Missing non-critical vendor report
  • Residential and mailing address do not match

High Risk Rules

  • Applicants in this bucket must complete Mitek verification
  • Name to bank account mismatch
  • Missing device profile
  • Negative bank account history
  • Suspicious device profile
  • Fraud model high risk
  • Young bank account
  • Young email address and young bank account and VoIP phone
  • Virtual machine use

Account Verification

More Info

The Amount platform facilitates validation and verification of an applicant's account information using a combination of third party data-driven, applicant-driven, and agent-driven workflows. Default configurations prioritize lowest-friction options first in order to increase applicant approval rate and reduce reliance on manual document reconciliation as an account verification technique.

Automated Open Banking - Finicity

Finicity enables applicants to use their online banking credentials to provide confirmation or ownership and authenticity of account information.

Manual Entry - Giact or ValidiFI

Giact or ValidiFI are fraud data sources Amount will leverage when an applicant chooses to manually enter their Account / Routing Number for account connectivity for disbursement. Account / Routing Number Validation and Account Ownership Validation are performed and if necessary Statement or Voided Check uploads may be requested.

Featured Vendors

Compliance Screening

More Info

Amount has partnered with ComplyAdvantage to screen applicants against the OFAC (Office of Foreign Assets Control) - SDN (Specially Designated Nationals and Blocked Persons) sanctions list. Applicants flagged as possible hits pending until an AML (Anti-Money Laundering) / BSA (Bank Secrecy Act) investigator reviews the application for risk and either rejects the application or resolves a task as a condition of approval.

OFAC

BSA

Sanctions

AML

Featured Vendors

Manual Review / Operations Tasks

More Info

Any application that has been soft declined because it did not pass a step in Amount's Intelligent Decisioning Waterfall or requires additional manual review is presented to authorized Financial Institution agents (Underwriter, Operations, Compliance, Member/Customer Support, Credit Risk, and/or Fraud Prevention) for decisioning. Authorized agents can also leverage Amount's AI Policy Optimizer and Rule Builder to make adjustments to policies where appropriate.

Application Review / Tasks

Applications are viewed in Amount's Queue Manager, which includes records of application activity, agent tasks, and third party reports.

  • Data Collection
  • Information Requested
  • Workflow Escalation
Identity Review / Tasks

Applications will be screened against an identity policy ruleset and flagged applications will be pending in a queue until an operations agent can manually review the application for identity risk and decision manually in Amount's Queue Manager.

  • KYC
  • Bank Account Verification
  • Name & DOB Verification
  • SSN Verification
  • Workflow Escalation
Credit Review / Tasks

Applications will be screened against a credit policy ruleset and flagged applications will be pending in a queue until a credit risk agent can manually review the application for credit risk and decision manually in Amount's Queue Manager.

  • Underwriting
  • Applicant Financial Data
  • Third Party Reports
  • Workflow Escalation
Fraud Review / Tasks

Applications will be screened against a fraud policy ruleset and flagged applications will be pending in a queue until a fraud agent can manually review the application for fraud risk and decision manually in Amount's Queue Manager.

  • Applicant Match
  • Risky Document
  • Workflow Escalation

Featured Vendors